How is Rolling Return calculated?
Let’s take an example to understand the calculation. Imagine you want to calculate a mutual fund's 3-year rolling return using its historical NAV data. You start by choosing the period you want to study. Let’s say you have 10 years of data and want to check 3-year returns.
You would then:
- Take the NAV from the starting date and the NAV three years later.
- Calculate the annualised return for that period.
- Move the starting date forward by one month or one year.
- Calculate the 3-year return again.
- Keep repeating this until you cover the available data.
Illustration:
Now you have several 3-year return figures. You can look at their average, lowest and highest values to understand how the fund behaved across different periods. Rolling returns are generally expressed as annualised returns for the chosen period.
Why are Rolling Returns useful?
The biggest advantage of rolling returns is that they show the fund’s consistency. Suppose a mutual fund shows a 15% return over the last 5 years. That sounds good.
But what if those five years happened to be an unusually strong period for the market? A single 5-year return won’t tell you how the fund performed during other 5-year periods.
Rolling returns give you a wider view. You can also see whether the fund has performed well during different market conditions, including periods of rising and falling markets.
How to analyse Rolling Returns?
You shouldn’t just look for the fund with the highest rolling return. Instead, look at a few things together, such as:
- Check the average rolling return: The average tells you how the fund performed across different periods you studied. A higher average can be useful, but don’t use it on its own to pick a fund.
- Look at the minimum and maximum: The lowest rolling return shows how much the fund performed during its weaker periods. The highest shows what happened during its stronger periods. A very wide gap between the two may indicate the fund’s performance has varied a lot.
- Check how often it beat its benchmark: You can compare a fund’s rolling returns with the rolling returns of its benchmark. If it beats the benchmark in most of its historical rolling periods, it may show stronger consistency.
- Compare funds in the same category: A small-cap fund should not be compared directly with a debt fund. Instead, compare similar funds and see how their rolling returns have behaved over the same periods.
Rolling Returns vs Point-to-Point vs Absolute Returns
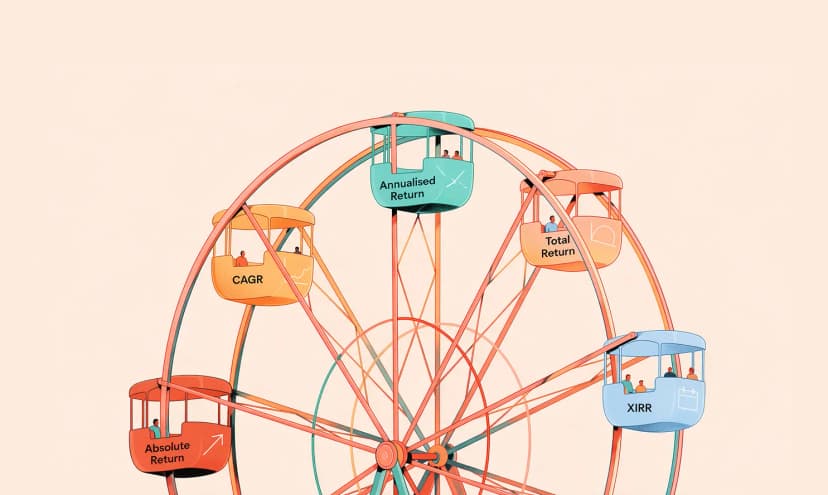
Each of these calculates mutual fund returns, but tells a different story.
Let’s say you check a fund from January 2021 to January 2026. A point-to-point return only looks at those two dates. Rolling returns could look at every 5 years available in the fund’s history. And absolute return simply tells you the total gain or loss percentage between where you start and where you end, completely ignoring the time in between.
What are the limitations of Rolling Returns?
- The result depends on the period: A fund’s 1-year rolling returns can look very different from its 5-year rolling returns. So, choose a period that matches how long you plan to stay invested.
- They can be difficult to calculate manually: You need a lot of historical NAV data to calculate rolling returns properly. Thankfully, most investment platforms provide this information.
- They don’t tell you everything about a fund: A fund may have good rolling returns but also carry higher risk. Before investing, look at other things too, such as the fund’s portfolio, riskometer, expense ratio, and investment strategy.
When should you check rolling returns?
Rolling returns can be used when you’re comparing different schemes for long-term investment. If you are planning to invest for 5 years, you can check the fund’s 5-year rolling returns.
Look at its average, lowest and highest returns. Then compare these figures with similar funds and the relevant benchmark.
The bottom line
Rolling returns of mutual funds help you look beyond one good or bad period and understand how the scheme has performed over time. You can use the rolling return data available on investment platforms to compare funds and understand their past consistency.
However, you shouldn’t let one return percentage decide everything for you. Choosing a suitable mutual fund is only one part of investing. Staying consistent, aligning your risks and goals, and giving your money enough time to grow also matters.