Types of Mutual Fund Returns
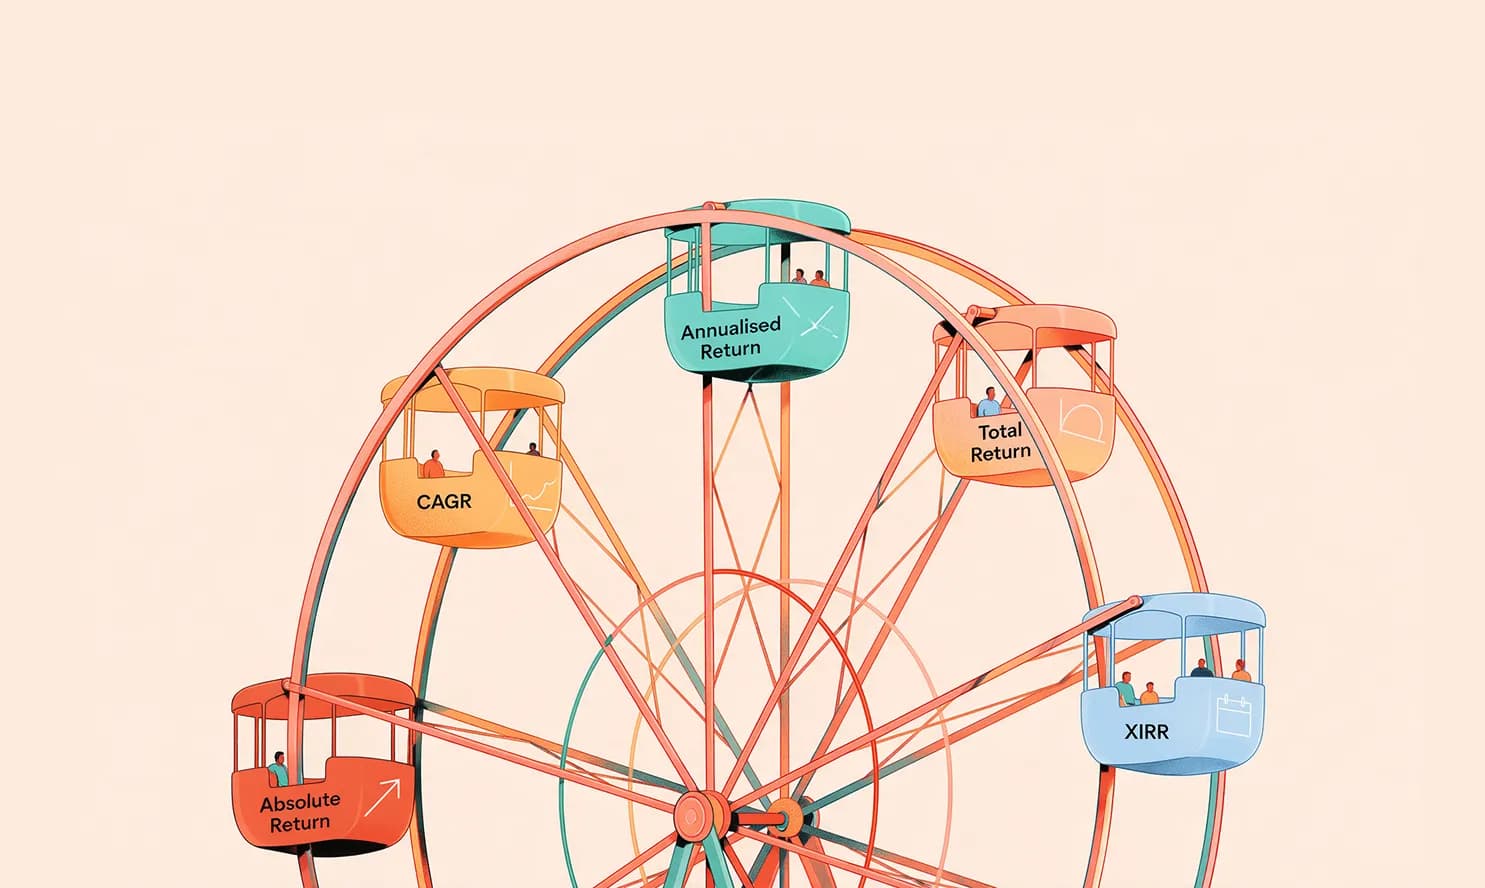
There are different methods by which mutual fund returns are calculated. Every method tells you in a different way how the mutual fund scheme has performed over time. Some show how the scheme performed over time, while others show average yearly growth. Understanding each type helps you evaluate performance accurately and set realistic expectations about mutual fund returns.
Here are the 8 types of mutual fund returns:
Absolute Returns
Absolute return tells you how much your investment has gained or lost in total. For example, you invest ₹10,000, and it becomes ₹12,000. Your absolute return is:
(₹12,000 - ₹10,000) / ₹10,000 x 100 = 20%
So, you made a 20% return. Absolute return does not consider how long it took to achieve that 20%. It is more useful only for shorter investment periods.
Annual Return
Annual return tells you how much the scheme has gained in one year. For example, if a fund’s NAV was ₹100 on January 1, 2025, and ₹112 on 31 December, 2025, its annual return would be:
(₹112 - ₹100) / ₹100 x 100 = 12%
This method can be used when you want to find out how the fund has performed in a single year. You can also compare different years to see how the fund behaved during good or bad market conditions.
Annualised Returns
Annualised returns tell you the average yearly rate of return over a particular period. Suppose you invested for 18 months and earned a 15% return. It becomes difficult to compare that return with another investment which was held for three years. Annualised return converts the performance into a yearly figure, making it easier to compare.
CAGR
CAGR stands for Compounded Annual Growth Rate. It gives you a yearly rate at which your investment would grow during the investment period. The formula is:
CAGR = (Ending Value ÷ Beginning Value)^(1/n) - 1
Here, n is the number of years.
Suppose you invested ₹10,000, and it becomes ₹14,641 after 4 years. The CAGR is 10%. This doesn’t mean the investment grew by the same percentage every year. It may have risen one year and fallen the next year.
XIRR
XIRR stands for Extended Internal Rate of Return. This method matters if you invest via SIP, as there are multiple instalments. Suppose you invest ₹1,000 every month. Your first ₹1,000 may have stayed invested for 2 years, whereas your latest ₹1,000 may have been invested only a few weeks ago. XIRR considers different investment dates and amounts.
Trailing Returns
Trailing return shows the fund’s performance from a particular date in the past till today. For example, you can see:
- 1-year trailing return
- 3-year trailing return
- 5-year trailing return
A 3-year trailing return looks at the fund’s performance for exactly the last 3 years from today’s date. This is useful for getting a quick picture of recent performance.
Point-to-Point Returns
Point-to-point return shows the mutual fund scheme’s performance between two dates. For example, you can check how the fund has performed between 1 Jan 2021 and 1 Jan 2026. You simply compare the NAV on those two dates. This method is useful when you want to study a specific period.
Total Returns
Total returns give you a whole picture of your investment returns by including all the earnings it generates. They include dividends and interest along with NAV appreciation.
For example, imagine your investment grows from ₹10,000 to ₹11,000, and you also receive ₹200 in dividend distributions. Other methods focus only on capital appreciation and can easily miss the ₹200.
Rolling Returns
Rolling return considers how the mutual fund scheme performs through the overlapping years. For example, if you want to see how the scheme has performed over a 3-year period, you check returns for:
- 2018 to 2021
- 2019 to 2022
- 2020 to 2023
- 2021 to 2024
- And so on…
It is useful when you want to know if the fund’s performance has been consistent across different market conditions.
Which mutual fund returns should you consider?
Here’s a quick guide to help you pick the right method for the right situation:
You don’t have to calculate every type of return yourself. Most mutual fund platforms already show these numbers.
Factors that affect mutual fund returns
Several things can affect your mutual fund returns, such as:
- Type of fund: Different types of mutual funds (equity, debt or hybrid funds) have different risk and return characteristics.
- Market conditions: Interest rates, inflation, economic growth and market sentiment can affect securities held by the fund.
- Fund manager: In actively managed funds, investment decisions can directly affect performance.
- Expense ratio: A higher expense ratio can reduce the return you ultimately receive.
- Investment period: Short-term returns can change quickly. Looking at a longer period can give you a better idea about the fund’s performance.
- Benchmark: Don’t look at a fund’s return in isolation. Compare it with its relevant benchmark to see if it has outperformed or underperformed.
The bottom line
You can analyse a mutual fund’s performance in many ways. Calculating different mutual fund returns tells you how the fund has behaved in the past as well as how it is performing in recent times.
However, remember that a good return on its own doesn’t necessarily mean a fund is a good choice. You must also consider the risk you’re taking to earn that return. Always understand your risk appetite and investment time horizon before investing.