About the SIP
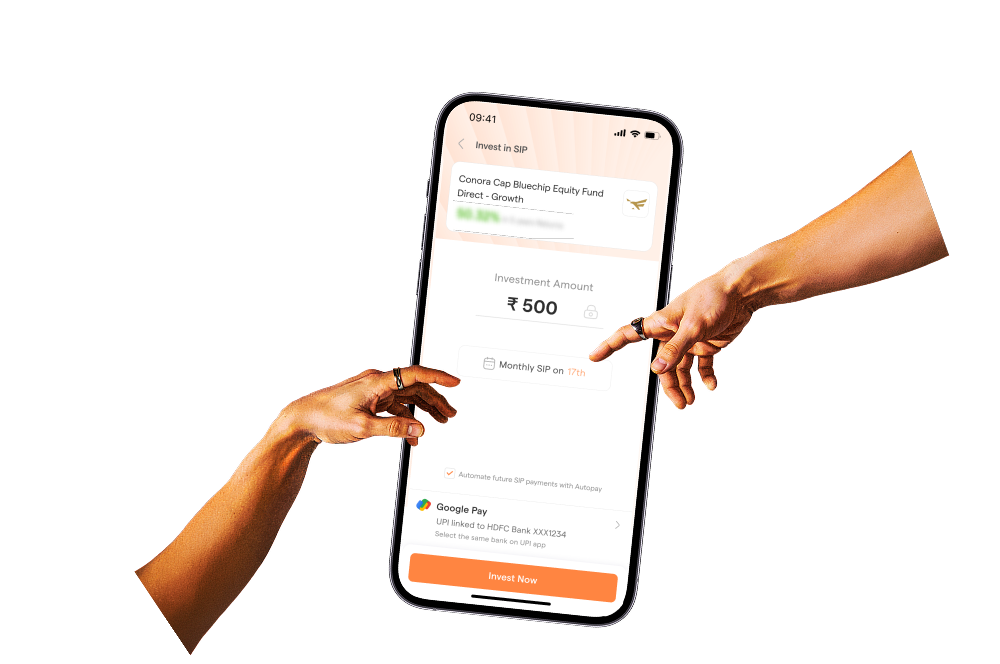
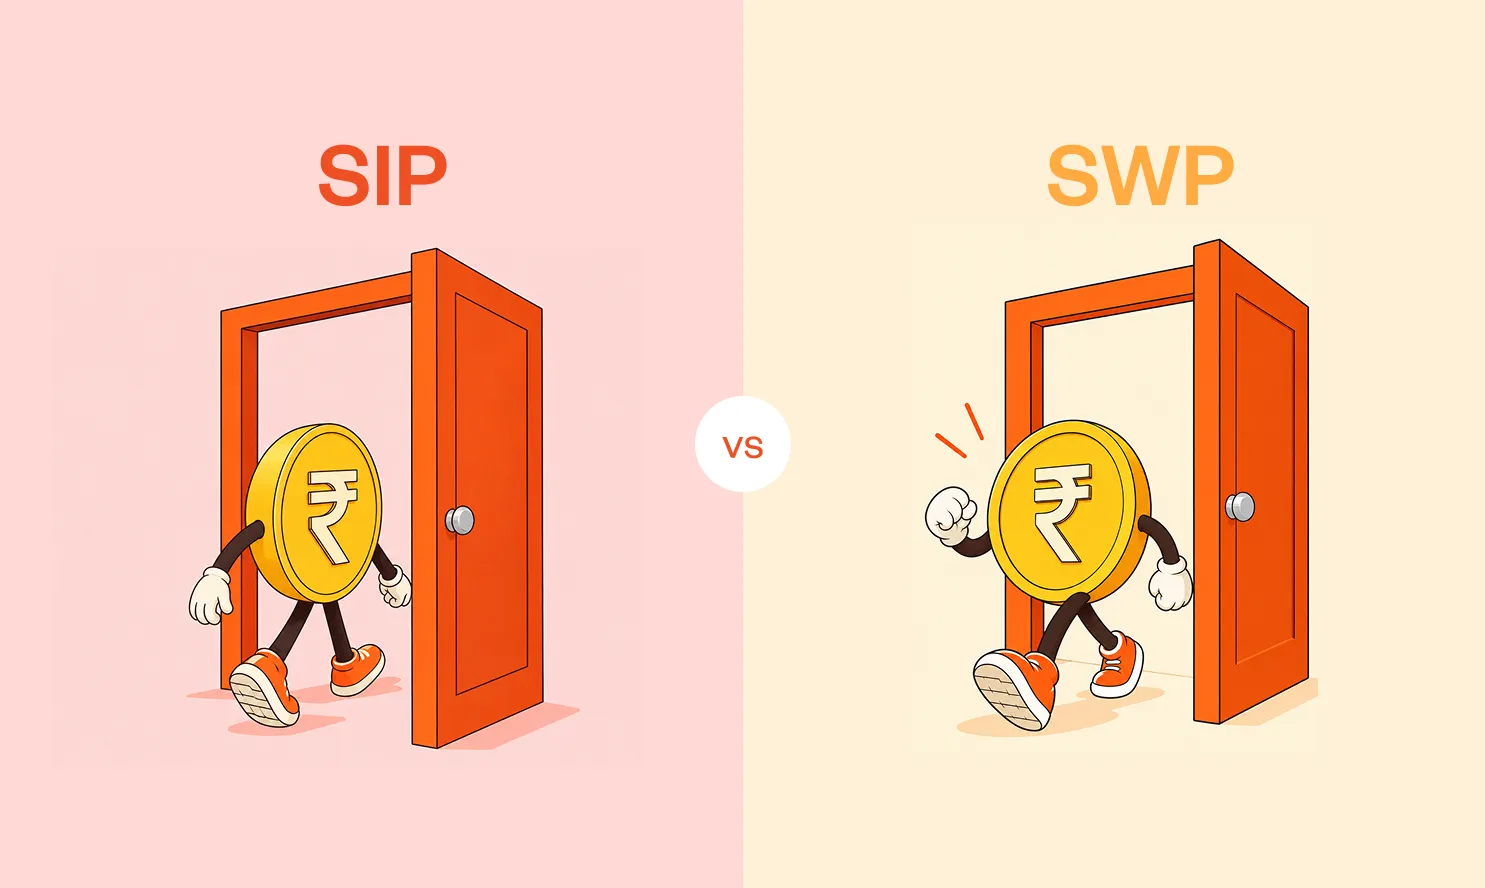
With a Systematic Investment Plan (SIP), you invest a fixed amount of money into a mutual fund on a regular basis. You can choose to invest daily, weekly or monthly. Once set up, your chosen amount is auto-debited from your bank account and invested on your chosen date. You can also start with a minimum investment of ₹100 per month. When your income or savings change later, you can adjust the amount or investment frequency.
Understanding SWP in mutual funds
A Systematic Withdrawal Plan (SWP) lets you withdraw a fixed amount from your mutual fund at regular times. It works well if you have built a good corpus and want to use part of it for daily expenses. Instead of letting all your money sit in a bank account, you can put it in a mutual fund and use an SWP to take out what you need every month. However, your investment carries market risk, and its value can go up or down with the market.
SIP vs SWP: How do they work?
Let’s understand how SIPs and SWPs work with the help of two practical scenarios.
Scenario A - SIP
Suppose you are saving ₹2,500 every month from your pocket money or salary for a Euro trip after 5 years. You decide to put this money into a mutual fund using a SIP. You invest ₹2,500 every month for 5 years. By the end of it, you would have invested a total of ₹1.5 lakh through 60 monthly instalments. The estimated final value of your investment would be around ₹2.06 lakh, assuming a 12% rate of return. Although this is just an estimate from the SIP calculator, the actual value may differ. The idea behind SIP is to let you invest a small amount regularly from your savings towards your goals.
Scenario B - SWP
Let’s say you have an existing ₹5 lakh mutual fund investment and need regular cash to handle monthly expenses. You can start an SWP to withdraw ₹5,000 each month. Over a year, you would withdraw ₹60,000. Units worth ₹5,000 are redeemed every month, based on the available NAV to withdraw the amount. If the NAV increases, fewer units are redeemed, compared to more units in case of a fall in NAV. Therefore, the balance in your fund may not be ₹4.4 lakh at the end of the year.
SIP vs SWP: A detailed comparison
Here’s an in-depth comparison between the two across various features.
While comparing, you should note that one option isn’t necessarily better than the other. They are meant for different situations. You may use a SIP when you’re building your savings. Years later, when you need money from those investments, an SWP may become useful.
SIP vs SWP: Which one should you consider?
The option you choose between SIP and SWP depends on your goal for that money. If you’re building long-term wealth, then you should consider SIP. It can suit you if you’re studying, have started working, or have some savings you want to invest regularly. You can start with an amount that fits your budget and increase it later.
For example, you may begin with ₹1,000 a month, and later, as your savings improve, you can increase the amount to match your financial goals. SIP can help you work towards long-term goals. The right mutual fund for SIP depends on your goal and risk comfort.
If you need regular withdrawals, then instead of SIP, you should consider SWP. This option makes sense if you’ve already accumulated a sizeable mutual fund investment and want to use some of that money for regular expenses. But before setting it up, check whether your investment can support the withdrawal amount for as long as you need it. Taking out too much can reduce your balance faster than expected.
The bottom line
Your financial needs won’t stay the same forever. When you’re starting your investment journey, you may want to invest a little from your savings. Later, you may have a larger investment that can help you pay your monthly bills. That’s where the SIP vs SWP comparison comes into the picture. Both the plans fit different stages of your financial journey.
Whether you want to set up a SIP or choose the SWP option, you can explore various mutual fund schemes on the Millions app. If you’re planning to start an SIP, start with an amount you’re comfortable with. As you learn more and gain confidence, you can make changes to your investment plan to match your goals.