Why absolute return doesn’t give a true picture
Since absolute return doesn’t take into account the duration of your investment, it gives only half the picture of its performance. Let’s say you invested in two mutual funds, Scheme A and Scheme B, and you want to compare which fund gave a better result.
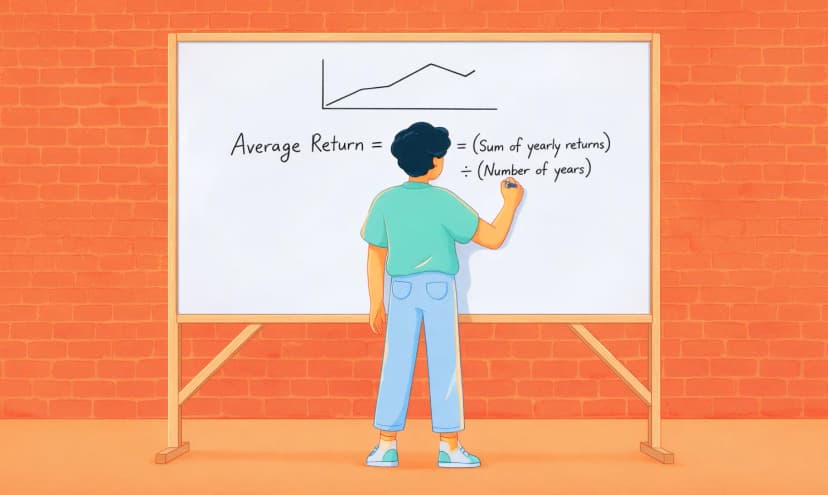
Scheme A gives you a 50% return in 5 years, whereas Scheme B gives you a 30% return in 2 years. Now, if you look at absolute percentages, you may consider that Scheme A, with a 50% return, has clearly given more returns. But if you take a simple average of the return per year, you’ll see that Scheme A has returned 10% per year and Scheme B has returned 15% per year. The answer changes.
So, if you are computing returns for an investment held for up to 1 year, absolute return can be used. But for investments with longer holding periods, there are better methods for more accurate calculations.
What is XIRR?
Extended Internal Rate of Return (XIRR) tells you your yearly return on your SIP investment. It considers every SIP payment you made and the date on which you made the payments.
Why does this matter? Well, every SIP payment you make stays invested for a different duration. Suppose you started an SIP a year ago. In that case, the first SIP instalment you paid was invested for 12 months. The next SIP instalment was invested for 11 months. Likewise, the last SIP instalment you paid was invested for only a month or less.
XIRR considers every SIP instalment one by one and gives you a single yearly return number. It is a personalised return based on your SIP investment amount and date. So, your XIRR can be very different from another person’s XIRR, even though you invest in the same scheme.
Absolute return vs XIRR: What’s the real difference?
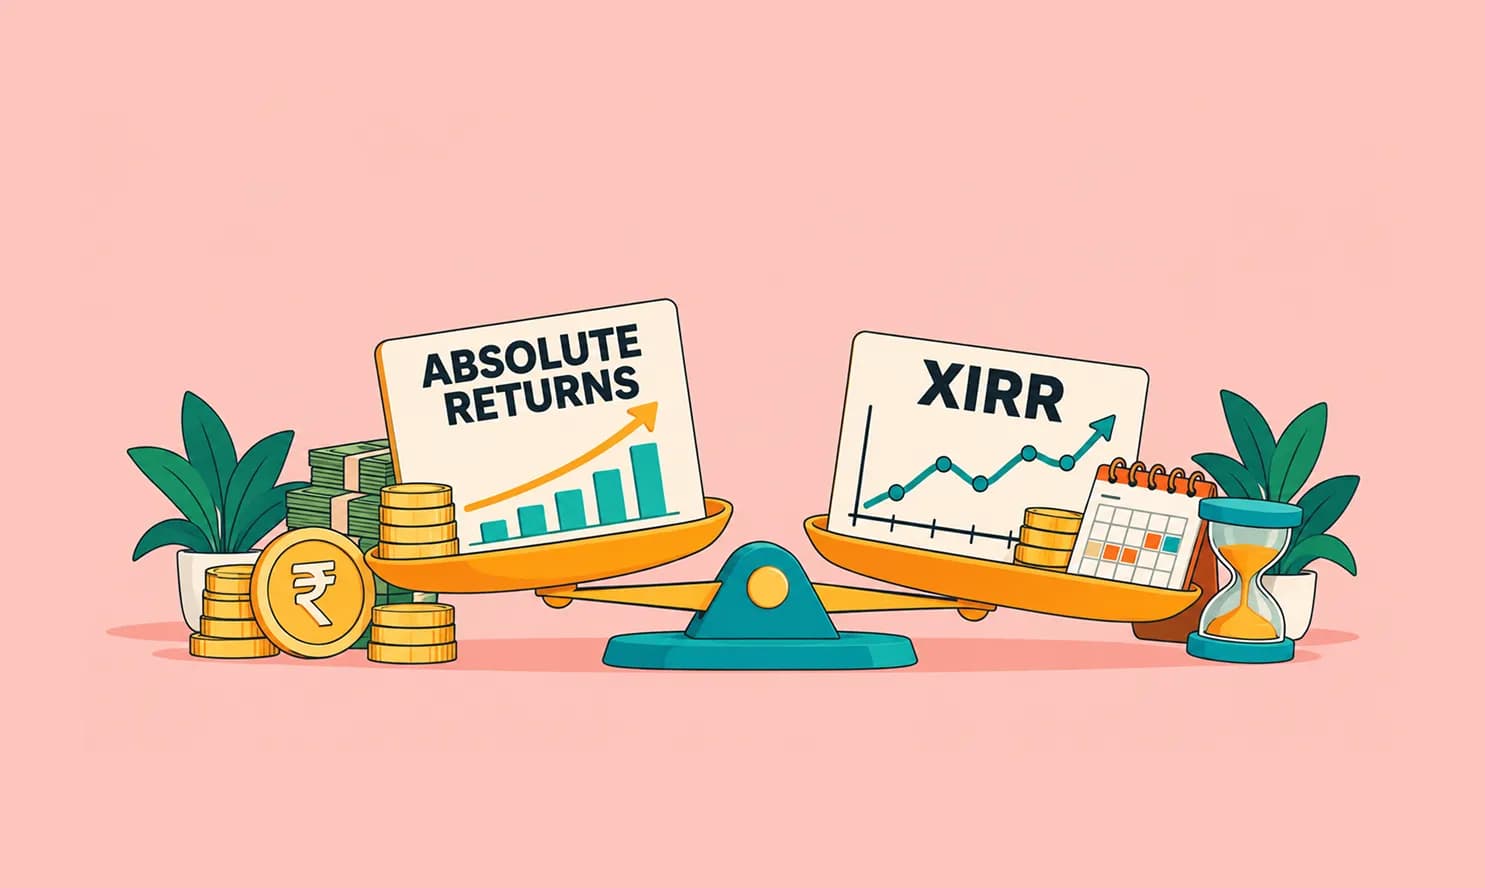
Absolute return and XIRR both tell you about your mutual fund returns, but they look at your investment differently. Absolute return only looks at how much your investment has grown, while XIRR also considers when you invested your money.
Absolute return vs XIRR: When to use which one?
The choice between absolute return vs XIRR depends on how you invested your money. If you made a one-time investment and want to know how much it has gained or lost, absolute return can be useful.
For SIPs, XIRR is more useful because each instalment is invested on a different date. It gives you an annualised return by considering every investment and its date.
If you are exploring more on XIRR, then XIRR vs CAGR might also be a helpful read for you.
Mistakes you should avoid
Many young investors often make mistakes while evaluating their mutual fund’s performance. Here are some mistakes you must avoid:
- Being too excited about short-term XIRR: XIRR can look very high over a short period, especially when the market has recently gone up. Don’t assume that the same return will continue for years.
- Tracking returns every day: Mutual fund returns can move up and down every day. Checking them constantly can make you focus too much on short-term market movements.
- Comparing different time periods: When the investment periods are different, the numbers don’t give you a fair comparison.
- Expecting past returns to repeat: A mutual fund that performed well in the past may not give the same returns in the future. Past performance is useful for analysis, but it is not a guarantee.
The bottom line
When comparing absolute return vs XIRR, remember that returns are only one part of your mutual fund investment. You don’t need to keep chasing the fund with the highest return or switch investments every time another fund performs better.
Review your investments occasionally, such as every quarter. This gives you a better view of your progress and keeps your focus on long-term wealth building. The bigger goal is to invest regularly, stay invested for the long term and give your money time to grow.