
3 year average returns
no. of funds
Low duration mutual funds maintain a macaulay duration between 6 and 12 months. Suitable for investors who seek higher returns than overnight or liquid funds, with limited interest rate exposure.
3 year average returns
no. of funds


Note: Past profits do not guarantee future returns.


invest in low duration funds
at 0% commission

Low duration funds are debt schemes that mainly invest in debt and money market securities, including government securities, corporate bonds, and other fixed-income instruments. As per SEBI's rules, these mutual funds must maintain a Macaulay duration of 6 to 12 months.
You can add these debt funds to your portfolio for short-term needs. They normally have lower interest rate risk compared to short-duration funds, which have a 1-3 year duration range.
These schemes' returns are market-linked. So, they aren't fixed like a regular bank deposit. The NAV can move up or down based on various factors like bond prices, interest rates, and credit ratings.
These funds may work for you if:
When you invest in this low duration scheme, the fund manager uses the money to buy different debt and money market securities. The portfolio is managed to keep its Macaulay duration between 6 and 12 months.
The fund earns money from the interest paid by its investments. It can also make or lose money when the prices of those securities change.
For example, suppose you invest ₹10,000 when the fund's NAV is ₹50. You receive 200 units (₹10,000/₹50). Now, if the fund's NAV move higher to ₹51, your 200 units would then be worth ₹10,200 (200 units x ₹51).
Your investment has gone up by ₹200 in this example. But the NAV could also fall. For example, if it moved to ₹49.50, your 200 units would be worth ₹9,900.
That's why you shouldn't treat low-duration funds like fixed deposits. The actual return depends on many factors such as underlying securities, credit quality, interest rates, and other market conditions.
These debt funds are similar in terms of duration, so it is easy to mix them up. Here are the main differences that separate them based on the type of securities they hold and other factors:
| Parameters | Low Duration Funds | Short Duration Funds | Money Market Funds |
|---|---|---|---|
| Invests in | Debt & money market instruments | Debt & money market instruments | Only money market instruments |
| Portfolio duration | 6-12 months | 1-3 years | 3-12 months |
| Interest rate risk | Low | Moderate | Low |
| Ideal investment horizon | 6 to 12 months or longer, depending on your goal | Around 1 to 3 years | Less than 1 year |
| Expected return | Moderate | Higher than low-duration funds | Matches existing repo rate |
| Volatility | Low | Moderate | Low |
| Who should invest | If you prefer shorter-duration debt funds | If you prefer to stay invested for a few years | If you prefer a short-term debt exposure |
The best low duration mutual funds aren't the ones with the highest returns recently. Always check whether the fund fits your own needs. Considering the following factors can help:
Remember, the best low duration funds for you are the ones that match your time frame and comfort with risk. If you need money very soon, you can consider overnight funds or liquid funds. For a slightly longer duration, short duration funds may be worth exploring.
To start a SIP in low duration mutual funds, download the Millions app on your smartphone and create a free account. Then follow a few simple steps:
Done! Setting up a SIP is that simple. You don't need to wait until you have a big bank balance to start investing. A regular SIP can help you gradually invest while you learn how debt funds work. As your goals change, you can explore other schemes such as liquid funds, short-duration funds or equity funds and build a portfolio that matches your needs.

They are generally lower-risk than many longer-duration debt funds, but they are not risk-free.
They both work differently. A savings account gives you easy access to your money, while a low-duration fund is a market-linked investment that could potentially give you a higher return.
Generally, low-duration funds are open-ended and do not have a mandatory lock-in period.
Yes, SIPs are available for schemes that offer the facility.
There is no single amount that works for everyone. Your investment should depend on your goal, income, and risk tolerance.
Debt-oriented low duration funds generally fall under the purview of Section 50AA. For covered investments, the profits are treated as short-term capital gains and taxed at your applicable income-tax slab rate.
You should prioritise easy access to emergency money. Depending on your needs, a savings account or a suitable short-term debt option may be more appropriate than relying entirely on a low duration fund.
need more help?
browse our support center for detailed guides and answers to common questions.
go to supportOpen your free Demat
account today

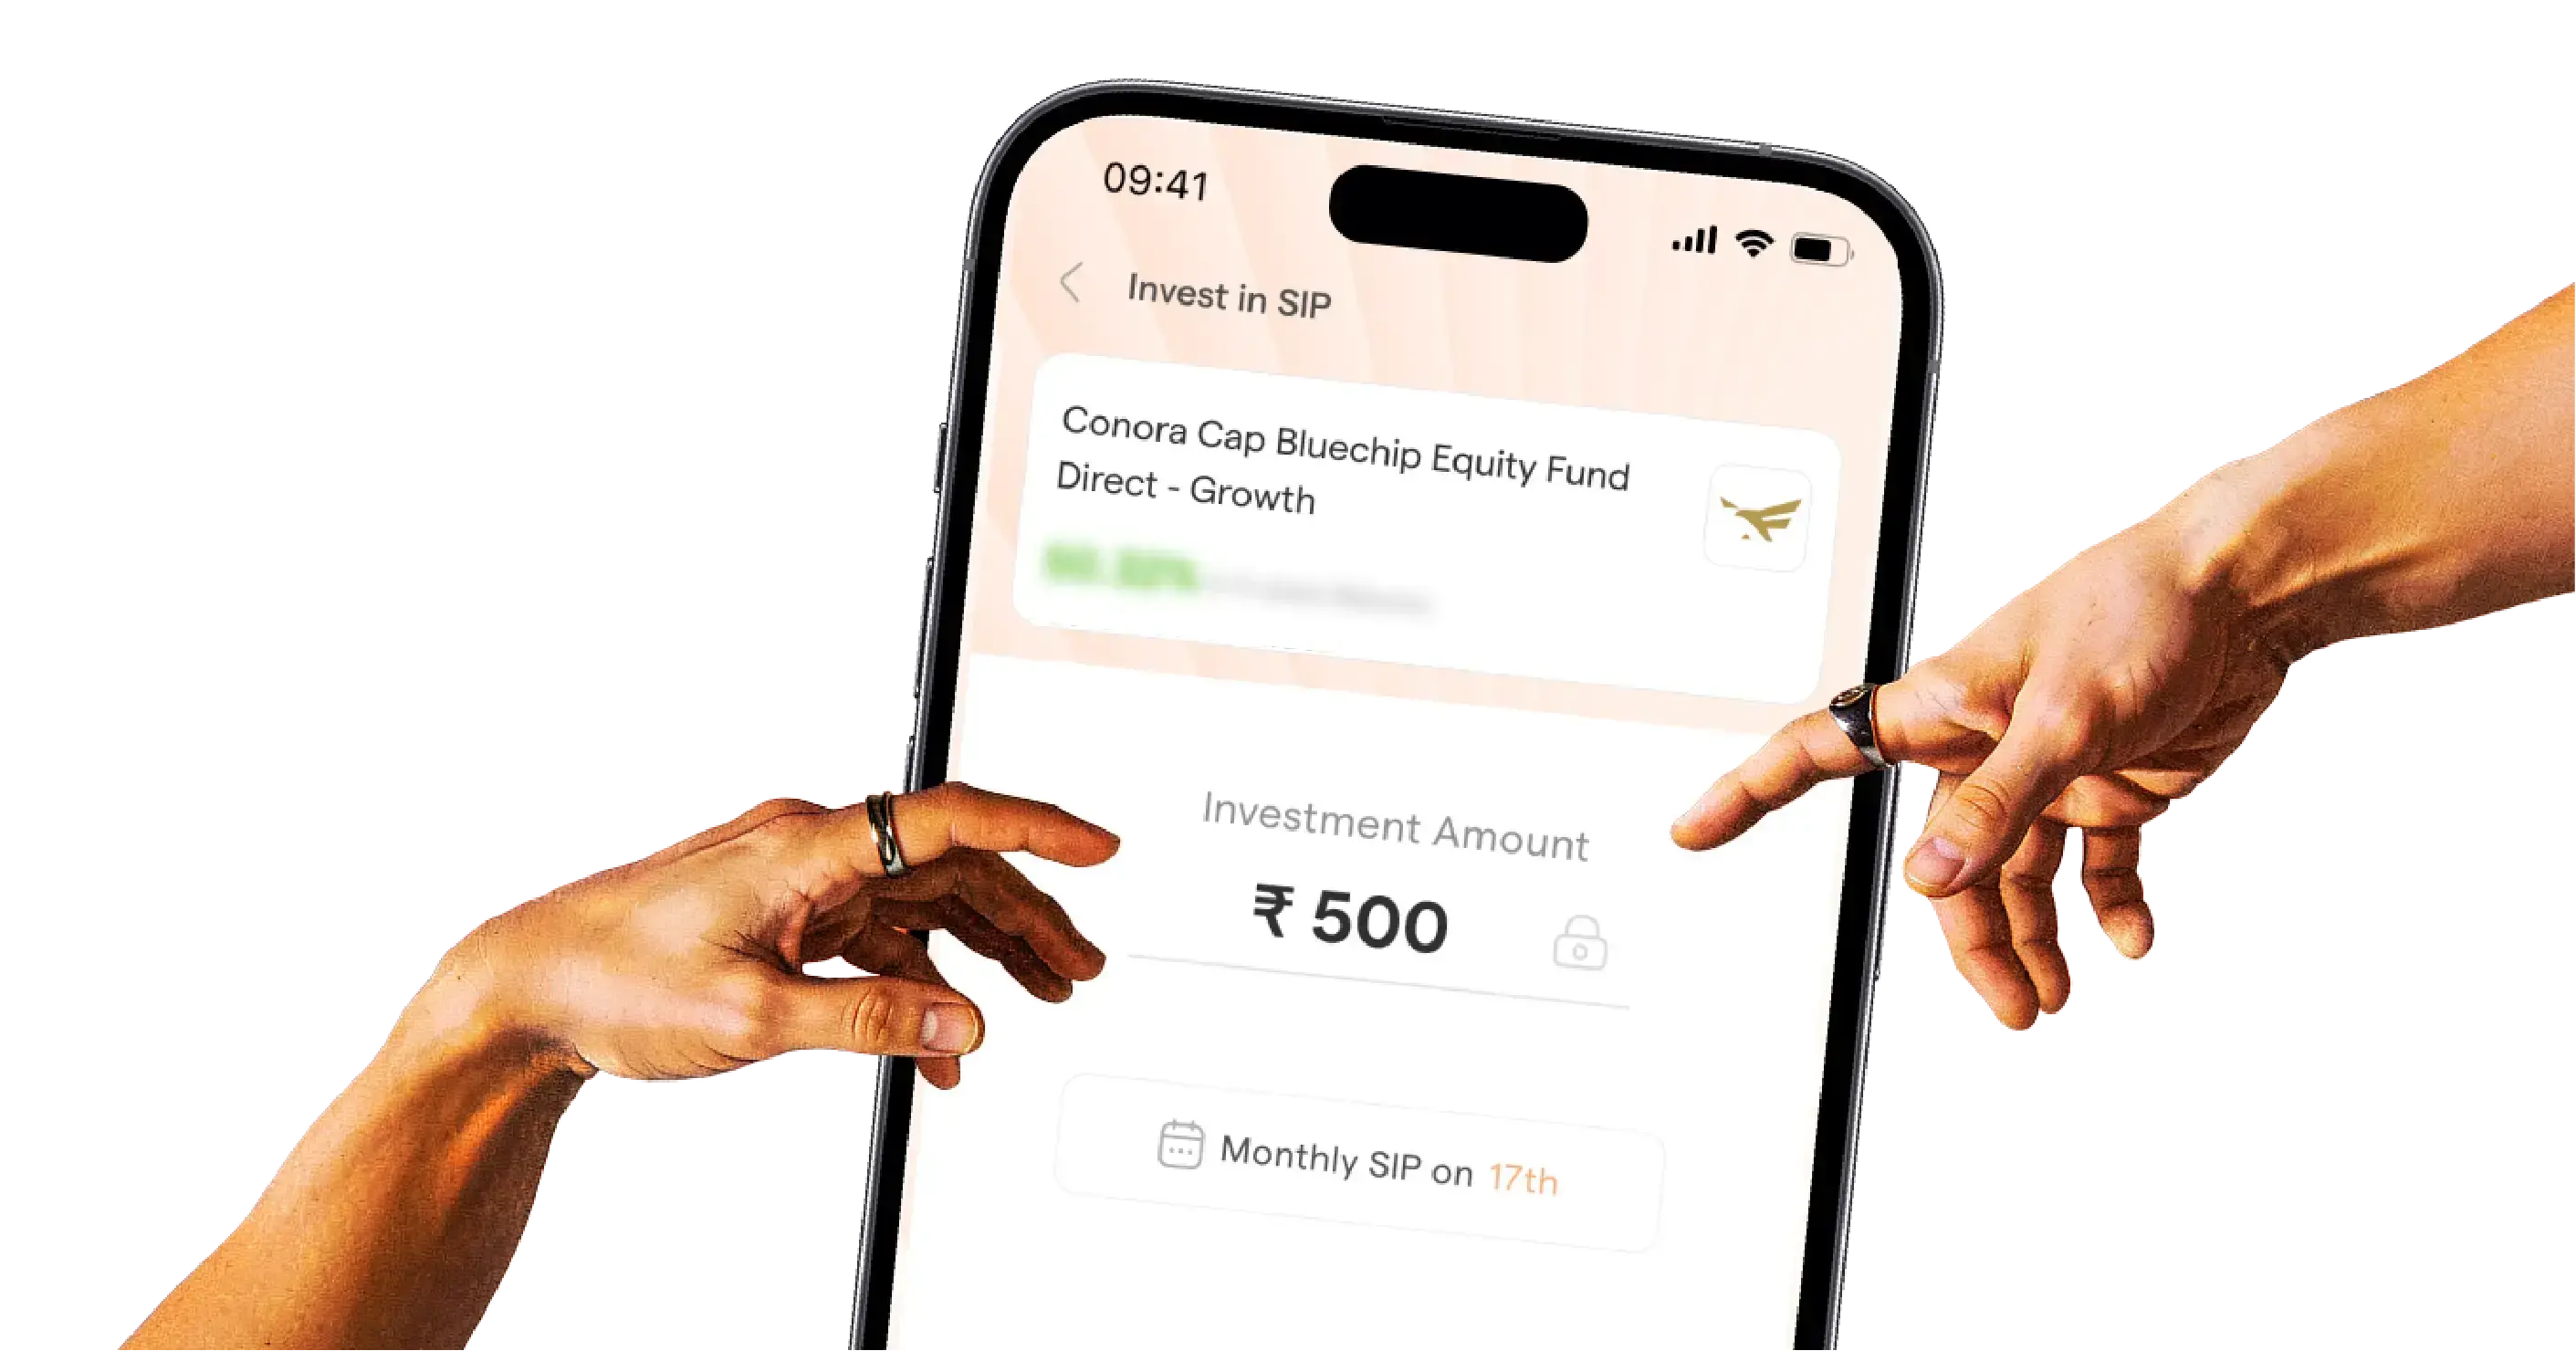
Open your
free Demat
account today

3 year average returns
0.00%
no. of funds
0
Low duration mutual funds maintain a macaulay duration between 6 and 12 months. Suitable for investors who seek higher returns than overnight or liquid funds, with limited interest rate exposure.
3 year average returns
0.00%
no. of funds
0
No funds available right now.
No funds available right now.
Note: Past profits do not guarantee future returns.
invest in low duration funds
at 0% commission
Low duration funds are debt schemes that mainly invest in debt and money market securities, including government securities, corporate bonds, and other fixed-income instruments. As per SEBI's rules, these mutual funds must maintain a Macaulay duration of 6 to 12 months.
You can add these debt funds to your portfolio for short-term needs. They normally have lower interest rate risk compared to short-duration funds, which have a 1-3 year duration range.
These schemes' returns are market-linked. So, they aren't fixed like a regular bank deposit. The NAV can move up or down based on various factors like bond prices, interest rates, and credit ratings.
These funds may work for you if:
When you invest in this low duration scheme, the fund manager uses the money to buy different debt and money market securities. The portfolio is managed to keep its Macaulay duration between 6 and 12 months.
The fund earns money from the interest paid by its investments. It can also make or lose money when the prices of those securities change.
For example, suppose you invest ₹10,000 when the fund's NAV is ₹50. You receive 200 units (₹10,000/₹50). Now, if the fund's NAV move higher to ₹51, your 200 units would then be worth ₹10,200 (200 units x ₹51).
Your investment has gone up by ₹200 in this example. But the NAV could also fall. For example, if it moved to ₹49.50, your 200 units would be worth ₹9,900.
That's why you shouldn't treat low-duration funds like fixed deposits. The actual return depends on many factors such as underlying securities, credit quality, interest rates, and other market conditions.
These debt funds are similar in terms of duration, so it is easy to mix them up. Here are the main differences that separate them based on the type of securities they hold and other factors:
| Parameters | Low Duration Funds | Short Duration Funds | Money Market Funds |
|---|---|---|---|
| Invests in | Debt & money market instruments | Debt & money market instruments | Only money market instruments |
| Portfolio duration | 6-12 months | 1-3 years | 3-12 months |
| Interest rate risk | Low | Moderate | Low |
| Ideal investment horizon | 6 to 12 months or longer, depending on your goal | Around 1 to 3 years | Less than 1 year |
| Expected return | Moderate | Higher than low-duration funds | Matches existing repo rate |
| Volatility | Low | Moderate | Low |
| Who should invest | If you prefer shorter-duration debt funds | If you prefer to stay invested for a few years | If you prefer a short-term debt exposure |
The best low duration mutual funds aren't the ones with the highest returns recently. Always check whether the fund fits your own needs. Considering the following factors can help:
Remember, the best low duration funds for you are the ones that match your time frame and comfort with risk. If you need money very soon, you can consider overnight funds or liquid funds. For a slightly longer duration, short duration funds may be worth exploring.
To start a SIP in low duration mutual funds, download the Millions app on your smartphone and create a free account. Then follow a few simple steps:
Done! Setting up a SIP is that simple. You don't need to wait until you have a big bank balance to start investing. A regular SIP can help you gradually invest while you learn how debt funds work. As your goals change, you can explore other schemes such as liquid funds, short-duration funds or equity funds and build a portfolio that matches your needs.
They are generally lower-risk than many longer-duration debt funds, but they are not risk-free.
They both work differently. A savings account gives you easy access to your money, while a low-duration fund is a market-linked investment that could potentially give you a higher return.
Generally, low-duration funds are open-ended and do not have a mandatory lock-in period.
Yes, SIPs are available for schemes that offer the facility.
There is no single amount that works for everyone. Your investment should depend on your goal, income, and risk tolerance.
Debt-oriented low duration funds generally fall under the purview of Section 50AA. For covered investments, the profits are treated as short-term capital gains and taxed at your applicable income-tax slab rate.
You should prioritise easy access to emergency money. Depending on your needs, a savings account or a suitable short-term debt option may be more appropriate than relying entirely on a low duration fund.
need more help?
browse our support center for detailed guides and answers to common questions.
go to supportOpen your free Demat
account today
Open your
free Demat
account today


